Life Insurance
Life Insurance Claim Documents: Maturity, Death Claims and Your Rights
FinSetu Editorial Team
Finance & Insurance Editorial Desk Published: Recent 13 min read
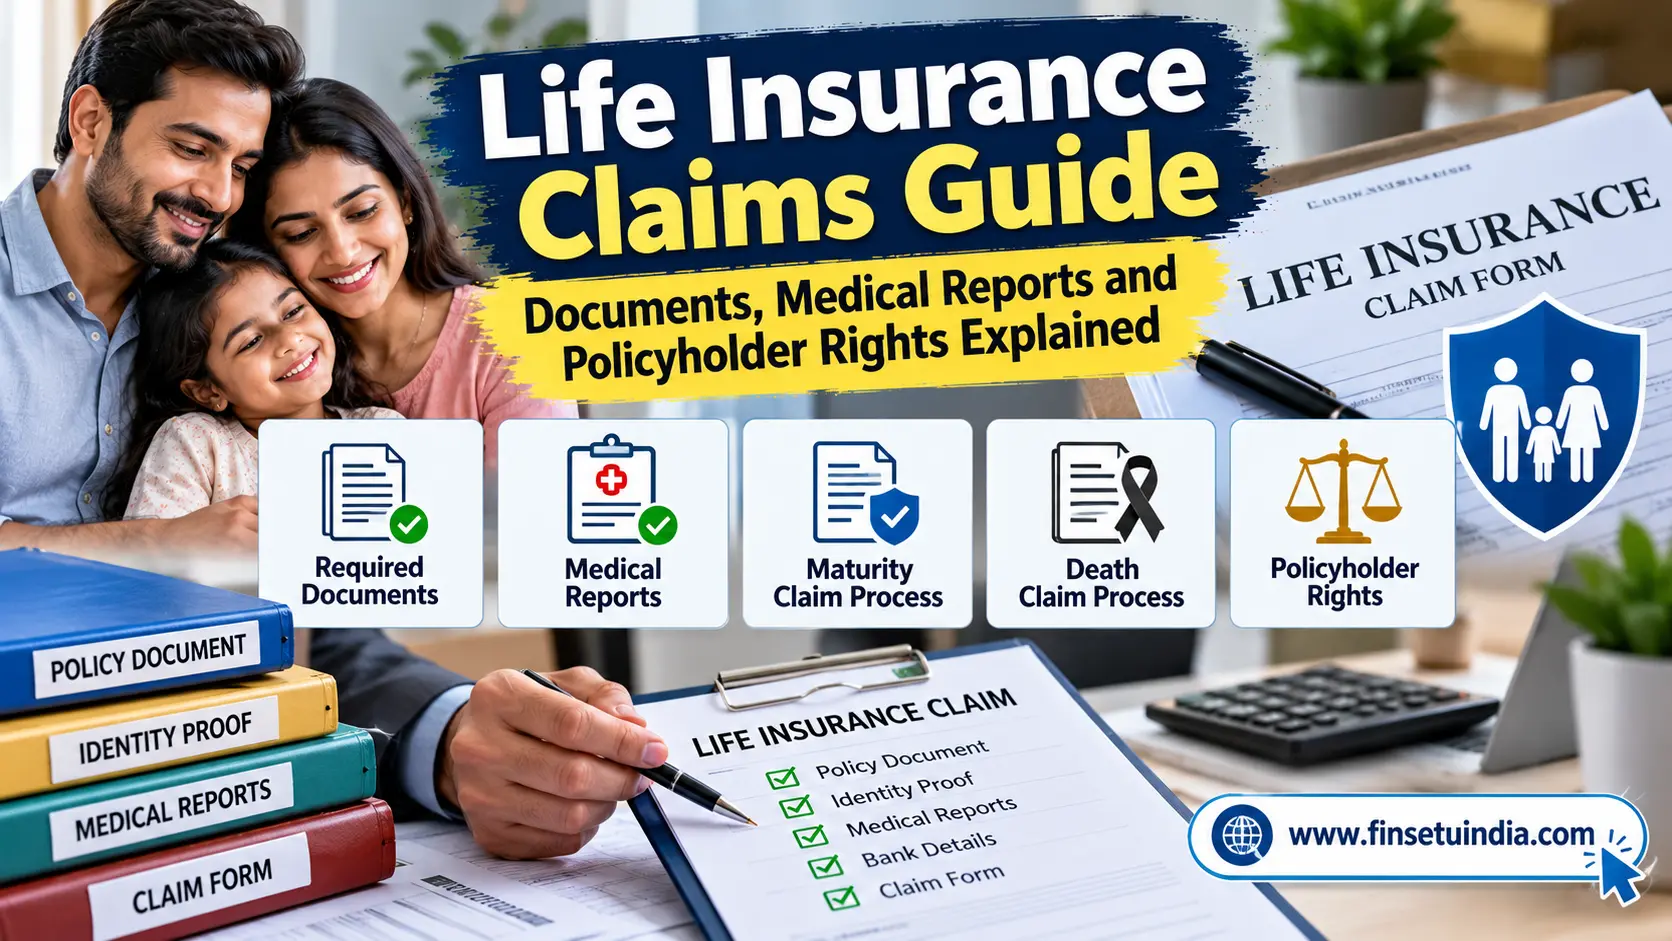
Life Insurance Claims Guide: Documents, Medical Reports and Policyholder Rights Explained
Life Insurance Claim Documents: Filing a life insurance claim can feel complicated, particularly when families are dealing with the loss of a loved one or policyholders are approaching the maturity date of their policy. Knowing which documents to prepare, when medical records may be required, and how the claim process works can help avoid unnecessary delays. In India, the documents required for a life insurance claim depend on the type of claim, the policy terms, the circumstances of the event, and the insurer’s verification requirements. A maturity claim generally involves the policy document, discharge form, bank details, and applicable KYC documents. A death claim may require a death certificate, claimant statement, identity and address proof, medical records, and police documents in accidental or other relevant cases. Policyholders and beneficiaries should also understand their rights under the applicable Insurance Regulatory and Development Authority of India (IRDAI) framework. This guide explains the usual documentation, the role of medical reports, claim timelines, and the steps to take if a claim is delayed or disputed.What Is a Life Insurance Claim?
A life insurance claim is a formal request to the insurance company to pay a benefit under the terms of a policy. The claim may arise when the policy reaches maturity, when the insured person dies during the policy term, or when another benefit becomes payable under the contract. The main types of life insurance claims include:- Maturity claim: A benefit payable when a policy reaches the end of its specified term, subject to its terms and conditions.
- Death claim: A benefit requested by the nominee, beneficiary, assignee, or other legally entitled claimant after the insured person’s death.
- Survival benefit: A scheduled payment under policies that provide benefits at specified intervals.
- Rider claim: A claim under an additional benefit attached to the policy, such as an eligible accidental death or disability benefit.
Documents Required for a Life Insurance Maturity Claim
A maturity claim is usually more straightforward than a death claim because it does not generally require proof of death or medical investigation. However, the exact requirements vary by insurer and product. Commonly requested documents include:- Original policy document: The policy bond or document issued by the insurer, where required.
- Completed discharge form: The form confirming the amount payable and authorising payment in accordance with the insurer’s process.
- Bank account details: A cancelled cheque, bank proof, or NEFT mandate, as specified by the insurer.
- Identity and address proof: KYC documents where required.
- Policyholder details: Policy number and any additional forms requested by the servicing branch.
- Assignment-related documents: Where the policy has been assigned, additional documents or instructions may apply.
Documents Required for a Life Insurance Death Claim
A death claim is usually submitted by the nominee or another person legally entitled to receive the policy benefit. The insurer needs to establish the insured person’s death, verify the claimant’s identity and entitlement, and determine whether the claim falls within the policy terms. The following documents are commonly requested, depending on the insurer’s procedure and the circumstances of the claim:| Document | Why It May Be Needed |
|---|---|
| Death certificate | To establish the death of the insured person. |
| Claimant statement or death claim form | To provide policy details, claimant information, and details of the event. |
| Original policy document | To verify the policy, where required under the insurer’s process. |
| Claimant’s identity and address proof | To verify the person submitting the claim. |
| Bank account proof | To arrange payment to the eligible recipient. |
| Nomination or legal entitlement documents | To establish who is entitled to receive the benefit, particularly where entitlement is unclear or disputed. |
| Medical or hospital records | To verify the cause and circumstances of death, where applicable. |
| FIR, inquest, or post-mortem report | May be required in accidental, unnatural, or other relevant deaths. |
When Are Medical Reports Required for a Life Insurance Claim?
Medical reports can be important in a death claim, but they are not necessarily required in every case. The insurer may request medical evidence to understand the cause of death, verify treatment history, or assess information relevant to the policy. Depending on the circumstances, the insurer may ask for:- Hospital admission records and discharge summaries.
- Medical attendant or treating physician certificates.
- Clinical notes and records of treatment before death.
- Diagnostic test reports relevant to the illness or event.
- Death summary or medical certificate stating the cause of death.
- Post-mortem report, where applicable.
- Police records, such as an FIR or inquest report, where relevant to the circumstances.
How to File a Life Insurance Claim: Step-by-Step Process
- Notify the insurer: Inform the insurance company as soon as reasonably possible after the event or when the maturity benefit becomes due.
- Obtain the correct claim form: Download the form from the insurer’s official website or request it from the servicing branch.
- Review the document checklist: Identify which forms, identity proofs, bank details, and supporting records apply to your claim.
- Submit the documents: Use the insurer’s authorised online portal, branch, or other accepted channel.
- Keep acknowledgement and copies: Save the claim reference number, submission acknowledgement, copies of documents, and all correspondence.
- Respond to queries: If the insurer requests clarification or additional documents, respond promptly and keep proof of submission.
- Track the claim: Use the insurer’s claim-tracking facility or customer service channel to check progress.
- Escalate unresolved issues: If the claim is delayed or the insurer’s response is unsatisfactory, follow the insurer’s grievance process and the applicable regulatory escalation channels.
Life Insurance Claim Settlement Timelines in India
Claim timelines depend on the type of claim and whether an investigation is required. Under the IRDAI’s 2024 Master Circular on Protection of Policyholders’ Interests, the stated timelines include:- Death claims not requiring investigation: Within 15 days from the date of claim intimation.
- Death claims requiring investigation: Within 45 days from the date of claim intimation.
- Maturity and survival benefits: On the due date, subject to the applicable requirements and policy terms.
Policyholder and Beneficiary Rights You Should Know
Policyholders and eligible claimants have important protections under applicable insurance law, regulations, and policy terms. These protections do not remove the need to establish entitlement to a benefit, but they help ensure that claims are handled fairly and transparently.- Access to claim requirements: The insurer should state the primary documents normally required for a claim in its policy documentation and make applicable requirements available to policyholders.
- Clear communication: Claimants should receive information about the status of their claim and any outstanding requirements.
- Reasons for a disputed claim: If an insurer disputes or rejects a claim, request the decision and reasons in writing, along with the relevant policy provisions.
- Timely processing: Claims should be processed within the applicable regulatory timelines, subject to the rules governing the particular claim.
- Grievance redressal: Policyholders can complain to the insurer if the claim is delayed, the document requirements are unclear, or the decision is disputed.
- Regulatory escalation: If the insurer does not resolve the complaint satisfactorily, the claimant may use the applicable IRDAI grievance channel or other appropriate remedy.
What to Do if a Life Insurance Claim Is Delayed or Rejected
If a claim is delayed, disputed, or rejected, take a structured approach rather than relying only on telephone conversations.- Ask for written clarification: Request the current status, outstanding documents, or specific reasons for the decision.
- Review the policy wording: Check the benefits, exclusions, conditions, nomination details, and relevant clauses.
- Submit a written complaint to the insurer: Include the policy number, claim reference, a timeline of events, copies of correspondence, and supporting documents.
- Keep acknowledgement: Save the complaint number and proof of submission.
- Escalate if unresolved: If the insurer does not resolve the issue within the applicable period or the response is unsatisfactory, consider the IRDAI grievance mechanism and other appropriate legal remedies.
Common Mistakes That Can Delay a Life Insurance Claim
- Submitting an incomplete claim form or leaving required fields blank.
- Providing bank details that do not match the eligible payee’s records.
- Failing to provide requested medical or police records where they apply.
- Ignoring follow-up communications from the insurer.
- Not keeping copies of submitted documents or the claim acknowledgement.
- Assuming every insurer requires exactly the same documents.
- Paying an unauthorised intermediary who promises guaranteed claim approval.
Life Insurance Claim Documents: Frequently Asked Questions
1. What documents are required for a life insurance maturity claim?
Common requirements include the policy document, completed discharge form, bank account proof or NEFT mandate, and applicable KYC documents. The exact list depends on the insurer and policy.2. What documents are needed for a life insurance death claim?
Common documents include the death certificate, claim form, claimant identity and address proof, bank details, and policy document where required. Medical records or police reports may also be requested depending on the circumstances.3. Are medical reports compulsory for every death claim?
No. Medical reports are not necessarily required in every case. The insurer may request them when relevant to the cause or circumstances of death, treatment history, or claim verification.4. How long does a life insurance death claim take in India?
Under the IRDAI 2024 Master Circular, the stated timelines are 15 days from claim intimation for death claims not requiring investigation and 45 days for claims requiring investigation. The applicable rules and circumstances of the individual claim should be checked.5. Can an insurer ask for additional documents?
Yes, additional documents may be requested when relevant to the claim. Check that the request comes from an authorised insurer channel, ask for clarification if necessary, and retain copies of everything submitted.6. What can I do if my life insurance claim is rejected?
Ask for the reasons in writing, review the policy terms, and file a formal grievance with the insurer if you disagree. If the issue remains unresolved, you may escalate it through the applicable IRDAI grievance channels or seek professional advice.7. Where can I complain about a delayed life insurance claim?
Start with the insurer’s grievance redressal channel. If the issue is not resolved satisfactorily, you can use the IRDAI Bima Bharosa portal and review the regulator’s complaint guidance.Conclusion
Preparing the correct Life Insurance Claim Documents can make the claims process easier for policyholders and beneficiaries. Maturity claims commonly involve policy and payment documentation, while death claims may require proof of death, claimant verification, and medical or police records where applicable. Understanding the insurer’s checklist, keeping written records, tracking the claim, and knowing the available grievance channels can help claimants protect their interests. Since requirements vary by insurer, product, and circumstances, always confirm the latest instructions with the insurance company and consult the applicable policy wording. Disclaimer: This article is for general information and consumer education only. It is not legal, financial, or insurance advice. Document requirements, claim timelines, and rights depend on the applicable policy terms and current regulations. Verify the details with the insurer and official regulatory sources before taking action. Sources: LIC – Claims Settlement Requirements | Life Insurance Council – Claims Process | IRDAI – Circulars | IRDAI – Bima BharosaInteractive Life Protection Tool
Human Life Value (HLV) Cover Calculator
Calculate pure term life insurance requirements based on annual income replacement, outstanding loans, family expenses, and inflation to age 60.
Transparent Methodology & Inputs
- Income replacement factor assumes 10x to 15x annual gross income
- Inflation adjustment accounts for 6% annual long-term living expense growth
- Includes 100% liability payoff for outstanding home loan or commercial debt
Limitation: HLV calculation provides a financial protection estimate for educational planning, not a binding insurance policy proposal.Official Citation: IRDAI Life Protection & Financial Underwriting Standards
#lifeinsurance#insuranceclaims#maturityclaim#deathclaim#policyholderrights#insurancedocuments#financialawareness#insuranceguide#personalfinance#finsetuindia