Health Insurance
Health Insurance Guide: Essential Precautions and Best Tips Before Buying a Policy
FinSetu Editorial Team
Finance & Insurance Editorial Desk Published: Recent 14 min read
Health Insurance Guide: Essential Precautions and Best Tips Before Buying a Policy
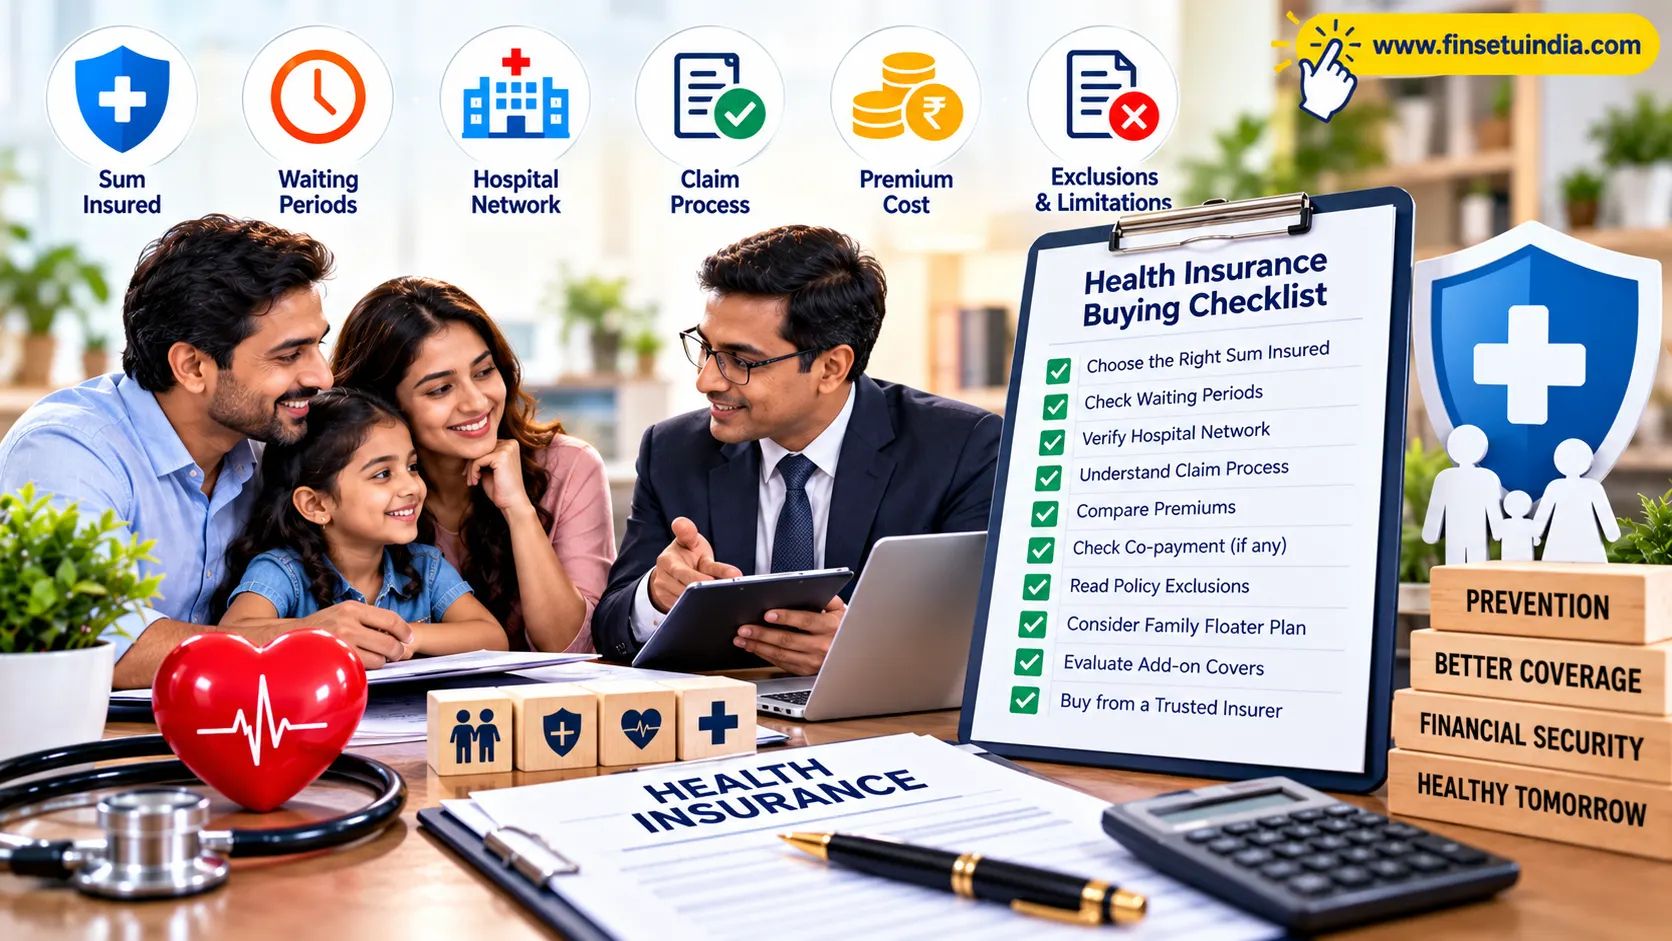
Health insurance can help protect your savings when a medical emergency or hospitalisation leads to substantial expenses. However, choosing a policy based only on a low premium or a large advertised sum insured can be risky. Waiting periods, exclusions, room-rent limits, co-payments, hospital networks, and claim procedures can all affect the benefits you actually receive. Before buying a health insurance policy in India, compare the coverage carefully and understand how the policy works in real-life situations. This guide explains the most important health insurance policy precautions, the questions to ask before purchasing a plan, and the steps you can take to choose suitable coverage for yourself and your family.Key Things to Check Before Buying Health Insurance
- Choose an appropriate sum insured for your family and location.
- Understand pre-existing disease and specific-treatment waiting periods.
- Check exclusions, co-payments, deductibles, and room-rent restrictions.
- Verify nearby network hospitals and cashless claim procedures.
- Disclose medical history and existing insurance accurately.
- Compare premiums alongside benefits, service conditions, and policy wording.
- Read the Customer Information Sheet (CIS) before making a decision.
1. Choose the Right Sum Insured
The sum insured is the maximum coverage amount available under the policy, subject to its terms, limits, and applicable conditions. It is one of the first factors to consider when comparing health insurance plans. A suitable amount depends on several factors:- The number of people covered under the policy
- Your family's age and healthcare requirements
- Medical treatment costs in your city
- Existing health conditions and likely treatment needs
- Your ability to pay the premium over the long term
- Whether you have employer-provided or other health insurance
Individual Health Insurance vs Family Floater
An individual policy provides a separate sum insured for the insured person. A family floater generally provides one shared sum insured that can be used by any covered member, subject to the policy terms.| Feature | Individual Policy | Family Floater |
|---|---|---|
| Coverage structure | Separate cover for each insured person | Shared cover for insured family members |
| Use of sum insured | Generally limited to the person's own cover | One member's claim can reduce the amount available to others |
| Best suited for | People who want separate coverage limits | Families seeking shared coverage under one plan |
2. Understand Waiting Periods Before Purchasing
A waiting period is the time during which specified illnesses, conditions, or treatments are not covered, as defined in the policy. A policy may have different waiting periods for different categories of treatment. Important types of waiting periods include:- Initial waiting period: Some illnesses may not be covered during an initial period after the policy starts, subject to the policy terms and applicable exceptions.
- Pre-existing disease waiting period: Disclosed conditions that existed before policy commencement may become eligible for coverage after the applicable waiting period.
- Specific disease or procedure waiting period: Certain listed conditions or treatments may have a separate waiting period.
- Waiting period on increased coverage: An increase in sum insured may be subject to fresh waiting-period conditions for the enhanced portion, depending on the policy and applicable rules.
3. Disclose Pre-Existing Diseases and Medical History Honestly
One of the most important health insurance policy precautions is to provide accurate information in the proposal form. Disclose medical conditions, previous diagnoses, ongoing medication, past surgeries, and other information requested by the insurer. Do not hide a health condition simply because it appears minor or is currently under control. Incorrect or incomplete disclosures can lead to disputes during claim assessment and may have consequences under the policy and applicable law. Before submitting your proposal:- Review every medical-history question carefully.
- Declare conditions and treatments requested by the insurer.
- Provide genuine medical records where required.
- Check that the proposal accurately reflects your answers.
- Keep a copy of the submitted form and relevant communications.
4. Read the Exclusions Carefully
Exclusions are situations, conditions, treatments, or expenses that a policy does not cover, or covers only under specified conditions. A plan with a high sum insured may still leave you paying substantial expenses if a relevant treatment or charge is excluded or restricted. Before buying a policy, check the exclusions for:- Specific treatments or procedures subject to policy restrictions
- Non-medical and administrative expenses
- Treatments related to pre-existing conditions during applicable waiting periods
- Expenses arising in circumstances specified as excluded in the policy
- Any permanent exclusion specifically applicable to the insured person
5. Check Room-Rent Limits, Co-Payments, and Sub-Limits
Some policies include limits that affect the amount payable for a hospitalisation claim. Understanding these restrictions is essential before comparing premiums.Room-Rent and ICU Limits
Some plans limit the amount payable for hospital room rent or intensive care unit charges. Choosing a room above the permitted category can affect claim payments if the policy contains proportionate deductions or related restrictions. Check whether the policy offers room-category restrictions, a specified monetary limit, or coverage without a room-rent cap, and understand how each option affects the claim.Co-Payment
A co-payment is the share of an admissible claim that the policyholder must pay. For example, if a policy has a 20% co-payment and the admissible claim is ₹1,00,000, the policyholder would generally pay ₹20,000 and the insurer ₹80,000, subject to other policy limits and conditions.Deductibles and Sub-Limits
A deductible is an amount the policyholder must bear before the insurer pays the covered balance, according to the policy terms. A sub-limit restricts the payable amount for a particular expense, treatment, or benefit. A lower premium may come with a higher co-payment, deductible, or more restrictive sub-limits. Compare these conditions against the amount you could comfortably pay from your own pocket during a medical emergency.6. Verify Network Hospitals and Cashless Treatment
Many insurers offer cashless treatment through a network of hospitals, subject to the policy and the insurer's authorisation process. Under cashless treatment, the insurer settles approved covered expenses directly with the hospital, while the policyholder remains responsible for non-payable expenses, applicable co-payments, deductibles, and other amounts not approved under the policy. Before buying a plan:- Check whether reputable hospitals near your home and workplace are in the insurer's network.
- Confirm that your preferred hospitals accept the relevant cashless arrangement.
- Review the process for planned and emergency hospitalisation.
- Understand pre-authorisation requirements and the documents the hospital may need.
- Ask what to do if cashless treatment is unavailable or authorisation is not granted.
7. Understand Claim Procedures and Required Documents
Before purchasing health insurance, find out how to inform the insurer about hospitalisation and how to submit a claim. Delays, incomplete documentation, or a misunderstanding of the process can create avoidable difficulties. Ask the insurer or intermediary to explain:- How to request cashless authorisation for planned hospitalisation
- How to notify the insurer during an emergency
- Which medical records and bills are required
- How reimbursement claims are submitted, where applicable
- How to track a claim and respond to document requests
- How to raise a complaint if a claim or service issue remains unresolved
8. Compare Premiums Without Compromising Essential Coverage
The premium is the amount you pay to maintain the policy. It is an important consideration, but the cheapest plan may not provide the coverage you need. When comparing premiums, review:- Sum insured and the scope of coverage
- Waiting periods and exclusions
- Co-payment, deductibles, and sub-limits
- Hospital network and claim-support arrangements
- Available restoration or no-claim benefits and their conditions
- Premiums at renewal and how pricing may change with age or other factors
- Taxes, payment terms, and any applicable charges
9. Check Restoration Benefits and No-Claim Benefits
Some policies offer a restoration benefit that may replenish the sum insured after it has been partly or fully used, subject to the policy conditions. Some also offer a no-claim bonus or cumulative bonus that may increase the available coverage or provide another defined benefit after claim-free periods. Do not assume these features work identically across insurers. Ask the following questions:- When does the restoration benefit become available?
- Can it be used for the same illness or the same insured person?
- Does the benefit apply to the first claim or only subsequent claims?
- How is the no-claim bonus calculated?
- Can the bonus be reduced after a claim?
10. Understand Renewal, Portability, and Continuity Benefits
Health insurance is most useful when coverage remains in force. Renew your policy on time and maintain records of payments and policy documents. A break in coverage can affect continuity benefits and may lead to new waiting-period requirements under the applicable rules. If you want to move to another insurer, investigate portability before the existing policy expires. Portability may allow eligible continuity credits to be carried over, subject to applicable rules and the receiving insurer's underwriting and acceptance process. Before changing insurers:- Compare the new policy's exclusions and benefits with your existing policy.
- Review how waiting-period credits and any other continuity benefits will be handled.
- Submit the portability request within the prescribed process and timeline.
- Do not cancel the existing policy until the replacement coverage and its terms are confirmed.
11. Read the Customer Information Sheet (CIS)
The Customer Information Sheet is a concise document that explains important features of a health insurance policy in simpler language. It can help you identify key conditions before reviewing the complete policy wording. Check the CIS for:- Type of policy and sum insured
- Covered benefits and major exclusions
- Waiting periods and sub-limits
- Deductibles and co-payments
- Free-look provisions and renewal conditions
- Portability and migration information
- Claims procedure and grievance-redressal contacts
12. Health Insurance Buying Checklist
Use this checklist before making your final decision:- Confirm the sum insured is suitable for your family and healthcare costs.
- Compare individual and family floater options, where relevant.
- Understand all applicable waiting periods.
- Disclose existing illnesses and medical history accurately.
- Read the exclusions and permanent restrictions, if any.
- Check room-rent limits, co-payments, deductibles, and sub-limits.
- Verify nearby network hospitals and cashless procedures.
- Understand claim notification, documents, and reimbursement procedures.
- Compare premiums alongside the coverage and renewal conditions.
- Read the Customer Information Sheet and full policy wording.
- Keep copies of the proposal, policy, payment receipt, and insurer communications.
- Save the insurer's customer-care and grievance contact details.
13. Frequently Asked Questions (FAQs)
Q1. What should I check before buying a health insurance policy?
Review the sum insured, waiting periods, exclusions, hospital network, room-rent restrictions, co-payments, deductibles, premium, renewal conditions, and claims process. Read the Customer Information Sheet and complete policy wording before purchasing.Q2. How much health insurance coverage should I buy?
The suitable amount depends on family size, age, location, healthcare needs, existing coverage, and affordability. Compare likely hospital expenses and choose a sum insured that offers reasonable protection for your circumstances.Q3. Should I disclose a disease that is already under control?
Yes, if it is requested in the proposal form or is otherwise required to be disclosed. Accurate medical disclosure helps the insurer assess the proposal and reduces the risk of later disputes.Q4. What is the difference between a waiting period and an exclusion?
A waiting period temporarily restricts coverage for specified conditions or treatments until the applicable period ends. An exclusion identifies circumstances or expenses that are not covered, or are restricted, under the policy. Check the exact wording for each condition.Q5. Does cashless treatment mean I will pay nothing at the hospital?
No. Cashless treatment generally means the insurer settles approved covered expenses directly with the network hospital. You may still have to pay co-payments, deductibles, non-payable items, expenses above limits, or amounts not approved under the policy.Q6. Is the cheapest health insurance policy the best choice?
Not necessarily. A lower premium may come with a lower sum insured, more restrictions, higher cost-sharing, or different benefits. Compare the full coverage and conditions before choosing.Q7. Can I change my health insurer later?
Portability may be available under the applicable rules, subject to the required process and acceptance conditions. Compare the replacement policy carefully and avoid allowing the existing coverage to lapse before the new arrangement is confirmed.Q8. What is the Customer Information Sheet?
The CIS is a summary of important policy details, including coverage, exclusions, waiting periods, sub-limits, cost-sharing, renewal provisions, and claim or grievance procedures. Read it alongside the complete policy wording.Conclusion
Buying health insurance is an important financial decision, and the right policy should provide meaningful protection when medical expenses arise. Before choosing a plan, compare the sum insured, waiting periods, exclusions, hospital network, claim process, cost-sharing conditions, and long-term affordability. Disclose your medical history honestly, review the Customer Information Sheet, and read the complete policy wording instead of relying only on advertisements or verbal assurances. Taking these precautions can help you make a more informed choice and understand what your health insurance policy does—and does not—cover.Disclaimer: This article is for general information and educational purposes only. Health insurance coverage, exclusions, waiting periods, claim payments, and renewal terms depend on the applicable regulations and the specific policy contract. Verify the latest terms directly with the insurer or through official IRDAI resources before purchasing a policy. This article does not constitute personalised insurance, medical, or financial advice.
Official Sources and Further Reading
- IRDAI: Health Insurance Guidance for Policyholders
- IRDAI: FAQs on Health Insurance Regulations
- IRDAI: List of Health Insurers
- IRDAI: Official Circulars and Regulatory Updates
Published by: Finsetu India | Health Insurance and Personal Finance
Interactive Insurance Decision Tool
Family Health Floater Premium Calculator
Estimate family floater health insurance premiums based on age band, sum insured (₹5L–₹1Cr), room rent capping, and restored cover.
Transparent Methodology & Inputs
- Base sum insured levels calibrated for tier-1 & tier-2 hospital networks
- No Claim Bonus (NCB) calculation assumes 10–50% annual step-up without claims
- Pre-existing disease (PED) waiting periods assume standard 24–36 month terms
Limitation: Calculated figures represent indicative premiums. Final policy underwriting quotes are issued directly by IRDAI registered insurers.Official Citation: Insurance Regulatory and Development Authority of India (IRDAI)