Insurance
Powerful Savings Tools and Precautions: Smart Ways to Save Money
FinSetu Editorial Team
Finance & Insurance Editorial Desk Published: Recent 12 min read
Powerful Savings Tools and Precautions: Smart Ways to Save Money
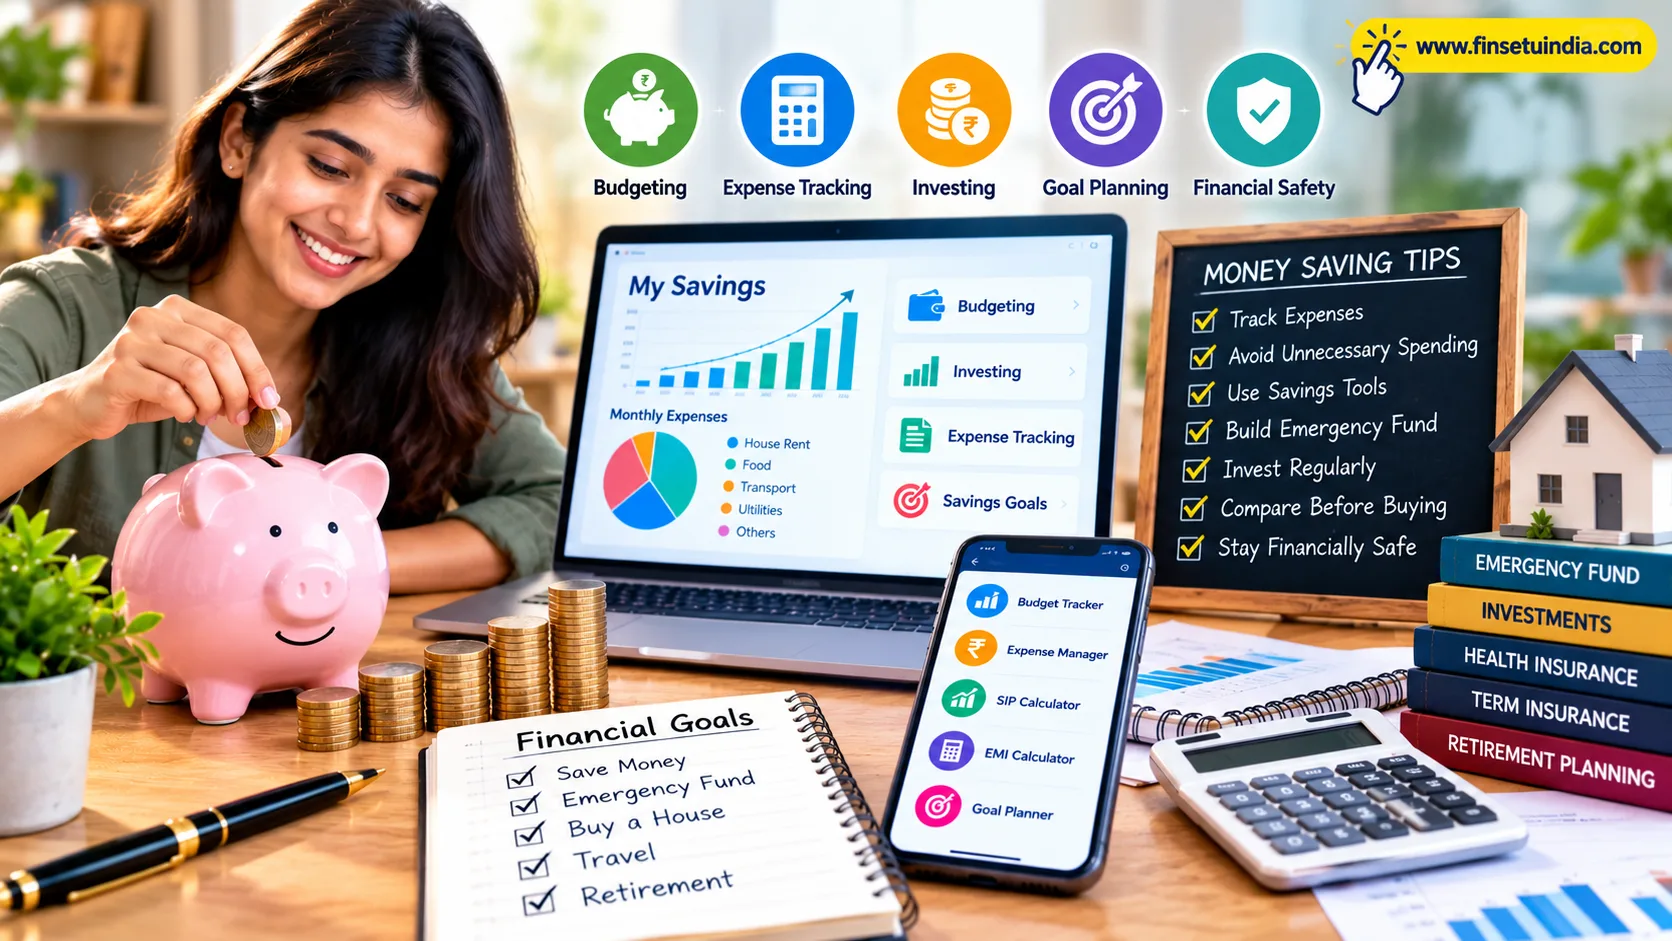
Saving money is not just about spending less. It is about making smarter financial decisions, managing everyday expenses, preparing for emergencies, and building a secure future. Whether you are a salaried employee, a business owner, a freelancer, or a student, the right savings tools and habits can help you take better control of your finances. From budgeting apps and expense trackers to automatic savings and bank deposits, several tools can make saving easier. However, choosing the right method and understanding the risks are equally important. In this guide, we explain some of the best money-saving tools, practical strategies to reduce expenses, and essential precautions to help you achieve your financial goals.Key Highlights
- Use budgeting tools to monitor income and expenses.
- Set aside savings regularly instead of waiting for money to be left over.
- Build an emergency fund for unexpected expenses.
- Reduce unnecessary subscriptions, impulse purchases, and avoidable charges.
- Compare financial products, fees, access conditions, and risks before choosing them.
- Stay alert to fake savings schemes and guaranteed high-return promises.
1. Why Is Saving Money Important?
Regular saving helps you prepare for financial uncertainty and meet future expenses without depending entirely on loans or credit cards. It can also help you work towards important life goals, such as buying a home, funding education, starting a business, or preparing for retirement. According to the SEBI Investor education website, savings can help people create an emergency fund and meet long-term financial goals. Some important benefits of saving include:- Financial security: Savings provide a reserve for unexpected expenses.
- Reduced borrowing: A financial cushion can reduce the need to rely on expensive loans.
- Goal planning: Regular contributions can help fund planned purchases and future responsibilities.
- Greater financial independence: Savings can give you more flexibility when making personal and professional decisions.
2. Best Money Saving Tools to Manage Your Finances
The best money-saving tool is one that fits your income, spending habits, financial goals, and comfort with technology. You do not need to use every available app. Start with a simple system that you can maintain consistently.A. Budgeting Apps and Expense Trackers
Budgeting apps and expense trackers help you record spending, organise expenses into categories, and identify where your money goes each month. Some tools allow manual entry, while others may offer bank or transaction integrations, depending on the service. Use an expense tracker to monitor categories such as:- Rent and household expenses
- Groceries and transportation
- Utility bills and mobile recharges
- Shopping and entertainment
- Loan repayments and insurance premiums
- Savings and investments
B. Monthly Budget Planner
A budget planner helps you compare your expected income with planned expenses and savings. It can be created using a spreadsheet, a budgeting application, or a simple written list. For example, if your monthly take-home income is ₹40,000, you could begin with the following illustrative budget and adjust it according to your circumstances.| Budget Category | Monthly Amount |
|---|---|
| Essential expenses | ₹22,000 |
| Personal and discretionary spending | ₹6,000 |
| Emergency fund contribution | ₹5,000 |
| Long-term savings or investments | ₹7,000 |
| Total | ₹40,000 |
C. Automatic Savings and Standing Instructions
Automatic transfers can help you save consistently without having to remember to move money every month. You can arrange a standing instruction through your bank to transfer a chosen amount into a separate savings account after your salary arrives. For example, saving ₹2,000 every month adds up to ₹24,000 in contributions over 12 months, excluding any interest. Choose an amount that you can maintain without missing essential bills or loan repayments.D. Savings Accounts and Bank Deposits
A savings bank account can provide convenient access to money for short-term needs. Depending on your requirements, you may also compare fixed deposits or recurring deposits for money you do not need immediately. Before choosing an account or deposit, check:- Applicable interest rate and how interest is calculated
- Minimum balance requirements and service charges
- Premature withdrawal conditions and penalties
- Deposit protection eligibility and applicable limits
- Ease of accessing your money when required
E. Bill Reminders and Subscription Trackers
Bill reminders can help you avoid late-payment charges and keep essential payments organised. Subscription trackers, calendar reminders, or a simple monthly checklist can also reveal recurring expenses that you no longer need. Review streaming services, premium memberships, app subscriptions, mobile plans, and other recurring charges. Cancel services that no longer provide sufficient value, and compare available plans before renewing.F. Savings Goal Calculators
A savings goal calculator can estimate how much you need to set aside regularly to reach a target amount by a chosen date. These tools are useful for planning a holiday, education expenses, a vehicle purchase, a home deposit, or another financial goal. For a basic calculation, divide your target amount by the number of months available. If you want to save ₹60,000 over 12 months, you would need to contribute ₹5,000 per month, excluding interest and any fees. For goals involving investment returns, remember that projected returns are estimates and may not be guaranteed.3. Practical Ways to Save More Money Every Month
Follow the Pay-Yourself-First Method
Instead of saving whatever remains at the end of the month, decide on a realistic savings amount when you prepare your budget. Move that amount to your savings account after receiving your income, while ensuring essential expenses and repayments remain covered.Differentiate Between Needs and Wants
Essential expenses include basic food, housing, utilities, healthcare, and necessary transportation. Wants may include optional upgrades, frequent dining out, impulse purchases, and services you can live without. Before making a non-essential purchase, ask yourself whether it is necessary now, whether it fits your budget, and whether a less expensive alternative would meet the same need.Plan Shopping and Compare Prices
- Prepare a shopping list before visiting a store or shopping online.
- Compare the final price, including delivery charges and taxes.
- Use discounts only when you genuinely need the product.
- Avoid borrowing money to take advantage of limited-time offers.
- Check return policies, warranties, and product quality before purchasing.
Reduce Food, Electricity, and Transportation Costs
Planning meals, reducing food waste, switching off unused electrical equipment, maintaining appliances, and combining errands can help control regular expenses. Where practical, compare public transport, carpooling, and other travel options. Small reductions in recurring expenses can create a useful amount of savings over time, particularly when the money saved is transferred into a dedicated account.Review Loans and Credit Card Costs
High-interest debt can make it difficult to build savings. Review outstanding balances, interest rates, fees, and repayment schedules. Prioritise a realistic debt-repayment plan while maintaining enough cash for essential needs and emergencies. Always pay at least the required amount by the due date and avoid treating a credit card limit as additional income. Paying only the minimum due can allow interest costs to accumulate.4. Build an Emergency Fund Before Taking Unnecessary Risks
An emergency fund is money kept aside for unexpected events, such as medical expenses, urgent home repairs, temporary income loss, or a business slowdown. The Reserve Bank of India's financial education material discusses keeping an emergency reserve that can cover at least three months of living expenses. People with less predictable income, business owners, and those with greater financial responsibilities may need a larger reserve, potentially covering six months or more. How to calculate your emergency fund: Emergency fund target = Essential monthly expenses × Number of months to cover| Essential Monthly Expenses | 3-Month Target | 6-Month Target |
|---|---|---|
| ₹15,000 | ₹45,000 | ₹90,000 |
| ₹25,000 | ₹75,000 | ₹1,50,000 |
| ₹40,000 | ₹1,20,000 | ₹2,40,000 |
5. Important Precautions When Using Money-Saving Tools
Protect Your Personal and Banking Information
Use official websites and trusted app stores when installing financial applications. Check the developer, permissions, privacy policy, and security features before linking accounts or sharing personal information.- Never share your OTP, UPI PIN, card PIN, or banking password.
- Do not approve unknown UPI collect requests or payment mandates.
- Avoid clicking suspicious links received through SMS, email, or social media.
- Use strong, unique passwords and enable additional security where available.
- Review account statements and transaction alerts regularly.
Beware of Guaranteed High Returns
A savings tool should help you manage money, not pressure you into an unsuitable financial product. Be cautious of schemes promising unusually high or guaranteed returns, referral-based earnings, or quick profits with little or no risk. Before investing, verify the provider and the product's regulatory status, understand the risks and charges, and read the official documentation. You can consult the SEBI Investor website's guidance on investment frauds.Understand App Charges and Withdrawal Restrictions
Some tools may charge subscription fees, transaction fees, withdrawal charges, or other costs. Certain products may also have lock-in periods, penalties, market risks, or differences between buying and selling prices. Read the terms carefully before depositing money. Do not assume that every product described as a savings feature offers the same protection as a bank deposit.Do Not Confuse Saving With Investing
Savings generally focus on preserving money and keeping it available for upcoming expenses. Investing aims to grow money over time but can involve losses and market fluctuations. Money needed for near-term essential expenses should not be exposed to risks you cannot afford. Consider your time horizon, financial situation, and risk tolerance before choosing an investment.Avoid Excessive Dependence on Cashback and Discounts
Cashback, reward points, and promotional offers can reduce the cost of a planned purchase, but they do not automatically create savings. Spending extra to qualify for a discount may leave you worse off financially. Compare the actual final cost and buy only what you need. A purchase you avoid entirely usually saves more than a reward earned on unnecessary spending.6. A Simple 30-Day Plan to Improve Your Savings
| Period | Action |
|---|---|
| Days 1–7 | Record your income, expenses, debts, and recurring payments. |
| Days 8–14 | Identify avoidable spending and prepare a realistic monthly budget. |
| Days 15–21 | Set up a regular savings transfer and begin building an emergency fund. |
| Days 22–30 | Review your progress, check fees, and adjust your spending plan. |
7. Frequently Asked Questions (FAQs)
Q1. What are the best money-saving tools?
Budgeting apps, expense trackers, spreadsheets, automatic bank transfers, bill reminders, and savings goal calculators are useful options. The best choice depends on your needs, budget, privacy preferences, and financial goals.Q2. How much money should I save every month?
There is no single amount suitable for everyone. Start with an affordable contribution after considering essential expenses, debt repayments, and family responsibilities. Increase the amount when your financial situation allows.Q3. How much should I keep in an emergency fund?
A common starting target is three months of essential living expenses. If your income is irregular, you run a business, or you have significant dependants, consider building a larger reserve based on your circumstances.Q4. Are money-saving apps safe?
Safety depends on the app, its provider, its permissions, and how it handles your data. Download apps from official sources, review privacy and security information, avoid sharing confidential credentials, and verify any financial product connected to the app.Q5. Are cashback offers an effective way to save money?
They can reduce the cost of purchases you already planned to make. However, buying unnecessary items just to earn cashback can increase your total spending.Q6. Should I save money or invest it?
Both can serve different purposes. Build accessible savings for emergencies and near-term needs, then consider suitable investments for longer-term goals according to your risk tolerance and time horizon.Q7. How can I save money on a low income?
Track essential expenses, reduce avoidable recurring costs, plan purchases, and start with a small but realistic savings amount. If your budget leaves no surplus, focus on essential needs, debt management, and opportunities to improve income rather than taking unnecessary financial risks.Conclusion
Powerful savings tools can make money management easier, but lasting financial progress comes from consistent habits. A clear budget, regular savings, an emergency fund, and careful spending decisions can help you prepare for unexpected costs and work towards important financial goals. Start with one simple tool, review your expenses, and choose a savings target that fits your situation. Most importantly, protect your financial information, understand fees and risks, and avoid schemes that promise unrealistic returns. Small, regular steps can help you build stronger financial habits over time.Disclaimer: This article is for general financial education and informational purposes only. It does not constitute personalised financial, investment, tax, or legal advice. Financial products carry different risks, terms, and protections. Verify details with the relevant bank, regulated provider, or official authority before making financial decisions.
Published by: Finsetu India | Personal Finance and Money Management
Interactive Wealth Growth Tool
Mutual Fund SIP Compounding Calculator
Calculate future wealth accumulation through monthly Systematic Investment Plans (SIP), CAGR growth rate, and rupee cost averaging.
Transparent Methodology & Inputs
- Formula: M = P × ({[1 + i]^n - 1} / i) × (1 + i)
- Assumed annual rate of return (e.g. 12% CAGR) is illustrative based on historical index trends
- Does not account for exit loads or short-term capital gains tax (STCG) variations
Limitation: Mutual fund investments are subject to market risks. Historical return estimates are not guaranteed future outcomes.Official Citation: Association of Mutual Funds in India (AMFI) Guidelines
#moneysavingtips#savingstools#personalfinance#smartsaving#budgetplanning#financialplanning#emergencyfund#moneymanagement#savemoney#financialliteracy#savingsgoals#finsetuindia